I bought two cars from John Hughes in Victoria Park in 2024. This is what happened next: the finance, the extras rolled into my loans, and a repair that didn't fix anything. Every point here is backed by contracts, invoices, messages and emails I still hold.
By Ali, a Perth car owner · Last updated 18 November 2026
My message to you
Be very careful when you buy a car on finance. Don't fall into the traps on this page. Always get a price from at least one other dealer before you sign, and compare the interest rate, the fees and the total you will repay.
14.6%interest on my loan arranged inside the dealership
12.99%on the loan I arranged directly, same lender
≈ $8,900extra I'll pay over 5 years on two cars
3 minnotice to collect my car after a "repair"
00 — Watch first
My story in 100 seconds
Animated summary of my own experience. Figures are from my loan contracts.
01 — My story
What happened, in order
I buy a 2020 Mitsubishi Outlander from John Hughes. The loan is arranged by the finance office inside the dealership. A $1,995 "membership" is added to the loan.
I buy a 2020 Hyundai Kona Electric from John Hughes, $54,063.80. Same process. A $1,395 "membership" is added to the loan.
For my third car, bought elsewhere, I go straight to the broker across the road. Same lender. Rate 12.99%. No membership.
The Kona's electric motor fails. The car is at John Hughes for more than two months. I ask for a replacement car. They refuse and pay only for the days I couldn't work.
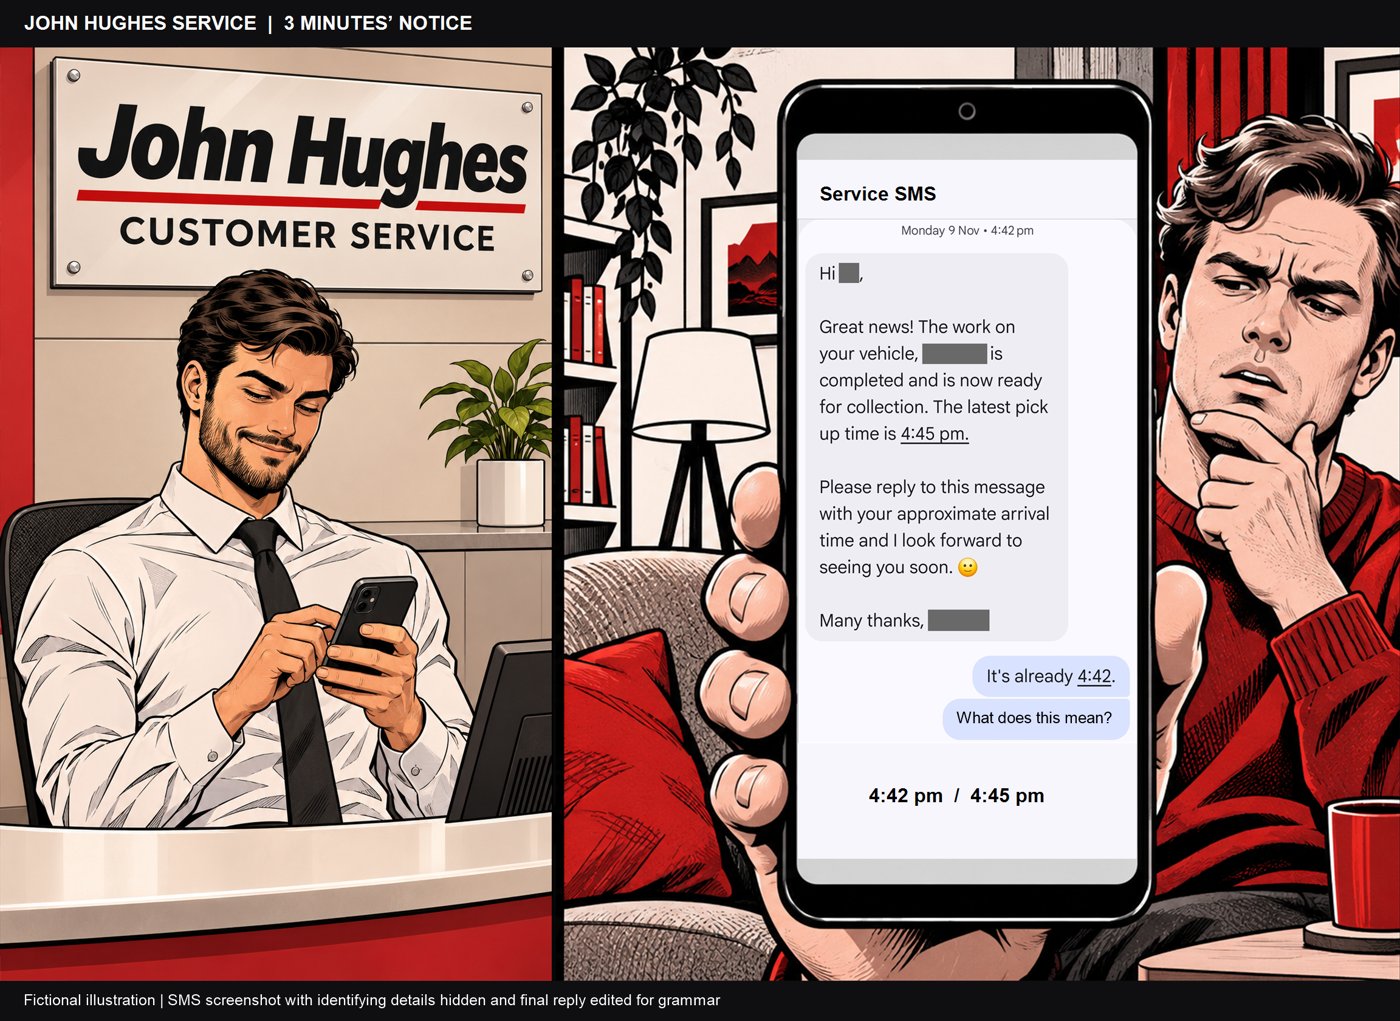
The Kona goes in for a steering vibration and knocking noise. At 4:42 pm I get a text: the car is ready, and the latest pick-up time is 4:45 pm.
I collect the car. The fault is exactly the same. Only now am I told a second, bigger part also needs replacing.
I call the service department three times. Each call is ended. My emails go unanswered.
The company emails me that it wants no dealings with me in future. I lodge complaints with Consumer Protection WA and Hyundai Australia.
02 — How the sale works
Four rooms, one goal
Buying a car at a big dealership isn't one conversation. In my experience it's a sequence, and each step is built to add to what you pay.
The car
A salesperson works hard to get you to say yes to the car. The price is above market, with no real discount.
Finance
A finance manager checks whether you qualify for a loan, and sets the rate.
The extras
A different room. Window tint, ceramic coating, a dash cam, a "membership". All at prices far above what you'd pay outside.
The loan
Every extra goes into the loan. You don't feel it because "it's only a few dollars a week". You pay interest on it for five years.
The car isn't where they make the money. The loan is.
03 — Two doors, two prices
Same lender. Same borrower. Different deal.
When I bought my cars, the loan broker across the road from the dealership, Yes Loans, was owned by the John Hughes Group. (The group sold it in mid-2026.) The finance officers inside the dealership arranged my first two loans. For my third car, I went to the broker directly. Same lender, within a year.
What I was charged
Arranged inside the dealership
14.35% / 14.60%
Outlander and Kona, 2024. Plus a "membership" financed into each loan: $1,995 and $1,395.
Arranged directly with the broker
12.99%
Third car, 2025. No membership.
If my two dealership loans had been set up like the direct one, I'd pay about $8,900 less over five years.
Rates calculated from the amount of credit, interest charge and 60 monthly repayments shown in my loan contracts. The cars, dates and deposits differ; the lender and the borrower are the same.
04 — The extras
Tint, coating, dash cam, membership
Neither car came with window tint as standard. Both had tint added as a paid extra. The Kona also had ceramic coating and a dash cam. Together these came to about $3,000 (my estimate) on top of the two memberships, and all of it was financed. At the time, I thought these came with the car.
In my experience at Westside Auto Wholesale in Perth, the cars came tinted and polished inside and out, and there was no membership. It could be a good place to get a second price. I have no connection with them; this is simply my experience. They also offer finance, tint and dash cams, so the same rules apply there: check the interest rate and say no to any extra you don't want.
The lesson: none of these extras is required to buy or finance a car. You can say no, or buy them later from a specialist for much less, and pay cash instead of five years of interest.
05 — The 5-year trap
What your car is worth when the loan ends
Most dealer loans run five years. By the last payment, the car is five years older, often out of warranty, and worth a fraction of what you paid. You're still paying interest on the tint and the membership you bought on day one.
Before you sign, ask yourself: what will this car be worth in five years, and how much will I have paid for it by then? On my two cars the answer is $64,080 and $67,884 in repayments, plus deposits.
06 — The service department
A repair that changed nothing
Illustration. The SMS is real; identifying details are hidden.
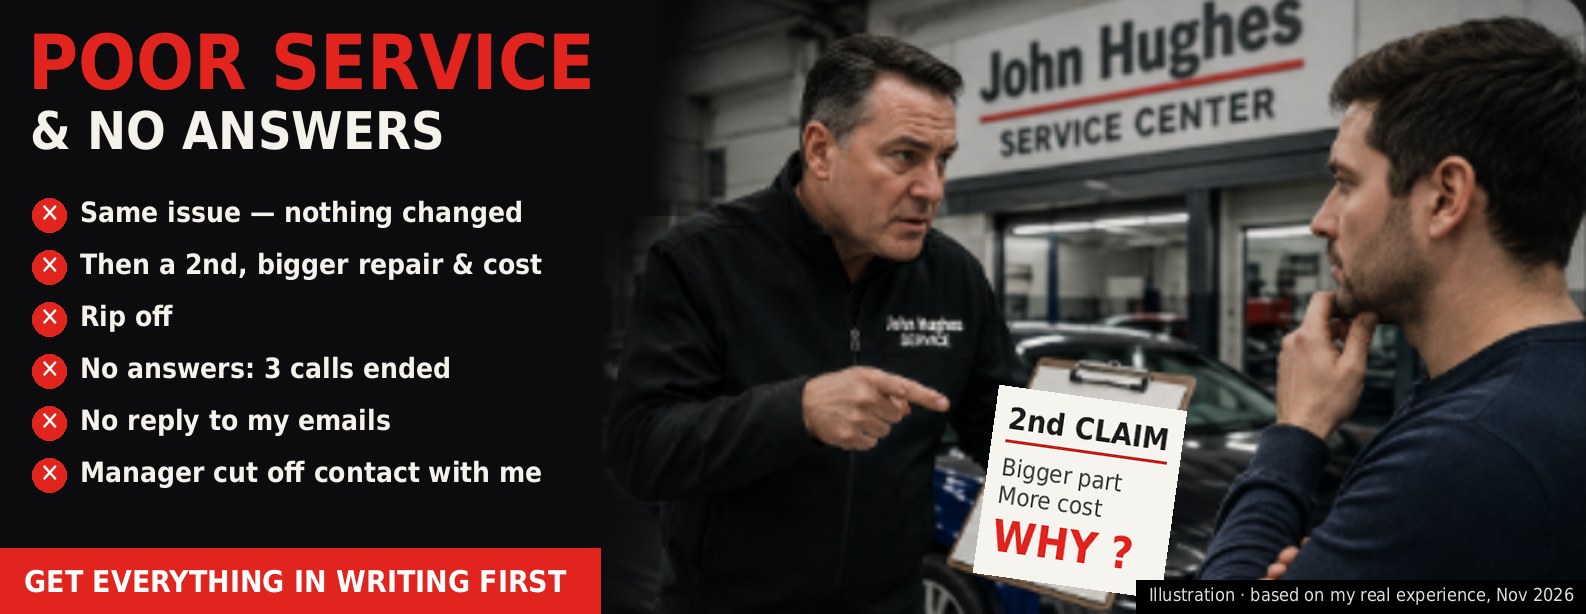
In November 2026 my Kona went in for a steering vibration and knocking noise. A part was replaced under my extended warranty. When I collected the car, the fault was exactly the same. Only after the first repair failed was I told a second, larger part also needed replacing, with more cost. It hadn't been found at the first diagnosis.
When I asked questions, my calls were ended three times in one afternoon. My written questions were never answered. Then the company told me it wanted no dealings with me in future, while my car is still under warranty.
Illustration, based on my real experience.
Under the Australian Consumer Law, services must be provided with due care and skill, and within a reasonable time. In my view, what I received fell well short of that. I have lodged complaints with Consumer Protection WA and Hyundai Motor Company Australia.
07 — Before you sign
A checklist for Perth car buyers
Get finance approved before you visit. A bank, credit union or independent broker gives you a rate to compare against.
Ask for the interest rate and the comparison rate in writing, and the total amount you'll repay.
Say no to extras in the finance office. Tint, coating, dash cams and memberships are optional. Get outside quotes first.
Check the loan amount line by line against the car price minus your deposit. Ask what every extra dollar is.
Take the contract home. Don't sign on the day under pressure.
For repairs, get every diagnosis, quote and cost in writing before you authorise work, and keep every message.
Had a similar experience?
Your complaint counts more in the right place than in a comment box. These are free: